
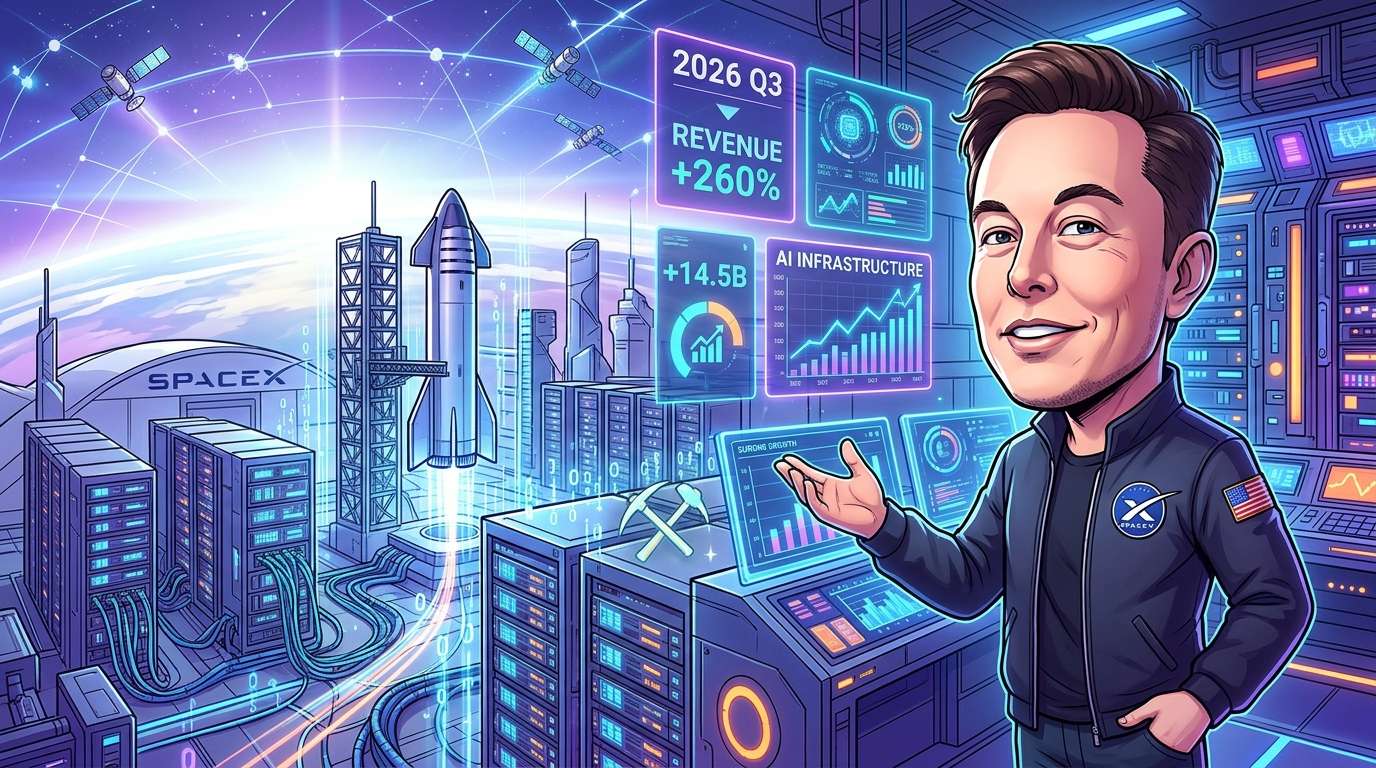
U.S. company SpaceX said on the 20th that its revenue for the July–September quarter of 2026 rose to $14.575 billion (about 2.3 trillion yen), 2.6 times the figure for the same period a year earlier, and that it swung to a net profit of $4.4 billion.
The AI division drove the revenue growth, with most of it reportedly coming from renting out computing infrastructure for AI.
The figures point to the strength of infrastructure rental, rather than AI itself
First, let’s take a look at the financial results. Revenue for the July–September quarter was $14.575 billion, up 2.6 times from the same period a year earlier. The company posted a net profit of $4.4 billion. It was a milestone quarter in which a company known for rockets and satellite communications began to be seen by the market as a growth company built around AI.
But a closer look at the figures changes the picture somewhat. The AI division that drove revenue growth consists mostly of equipment rentals, rather than sales of the company’s own AI services. When AI is in the news, attention inevitably turns to smart models and useful chat services. But in this case, the revenue came from the computing infrastructure needed to run those models.
There is a famous story that the real winners of the gold rush were the merchants who sold pickaxes and jeans. The AI boom may be playing out in a similar way. Here, equipment rental refers to providing companies with the computing capacity needed to train and run AI systems.
Investment swells behind revenue growth and a return to profit
Equipment rental can translate readily into revenue, provided there is demand. But the equipment has to be in place before it can be rented out. A key point in reading these results is that rapid expansion requires huge investment—and brings risks of its own.
Revenue up 2.6 times and a return to net profit may suggest that the investments are beginning to pay off. But as long as the company continues to add equipment, spending will continue too. The pace of growth and the scale of investment should always be considered together.
SpaceX released its first financial results in August this year. At the time, revenue for the April–June quarter was up about 90%, but the company posted a loss due to AI investment. It has now swung to profit in just one quarter. This may indicate that returns on investment are beginning to show up in earnings, but the next focus will be whether the company can remain profitable as investment continues.
What should we look at when we call a company an “AI company”?
Saying that a company has transformed itself into an AI company is easy to understand, but it can obscure what the business actually does. Does it develop and sell models, or rent out the infrastructure that runs AI? Even when revenue comes from the same AI division, the sources of income and the risks involved differ.
SpaceX’s latest financial results offer a useful case study for considering that distinction. It is important to look not only at the scale of an AI business, but also at what it sells to generate revenue. Even when the word “AI” appears in a news headline, getting into the habit of checking what the business actually does will become increasingly useful.
The AI race has two arenas: one in which companies compete over intelligence, and another in which they compete over the foundations that support it. SpaceX’s July–September results showed that the latter arena can generate substantial revenue.








Comments